What is a peril in insurance?
The definition of peril is a circumstance or event that results in property damage. While many things fit this definition, an important distinction for homeowners insurance is that a covered peril happens suddenly and directly causes damage.
While a peril in insurance is the cause of the damage, there may be other events leading up to it. In some cases, those events will determine whether the peril is covered or excluded.
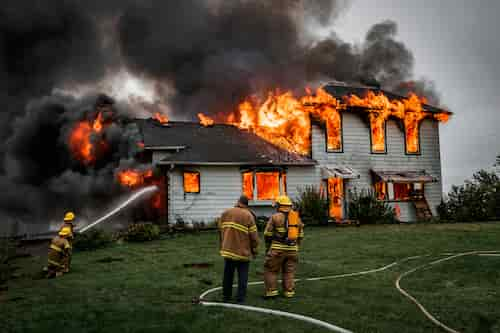
Imagine there’s a fire in your kitchen. Fire, in this case, is the peril, regardless of what caused it to start; it’s the thing that directly caused the damage, and it happened suddenly, without warning. Home insurance covers fire damage to your home and personal property.
Insurance companies cover damage caused by covered perils, and perils are either covered on an open perils or named perils basis. Named perils policies cover a specific list of perils, while open perils policies cover everything that is not specifically excluded. Standard homeowners insurance policies exclude many perils, most notably flooding and earthquakes.
A homeowner has a responsibility to protect the home from damage and to keep it in a state of good repair. A homeowners insurance company won’t pay for damage that happens due to wear and tear; a roof that is getting old and starting to leak, for example.
The resulting leak wouldn’t be covered by insurance; it could have been prevented by proper maintenance. In other words, it's not sudden and accidental damage.
However, if the roof is damaged by a severe storm and leaks as a result, the damage to your home and personal property will be covered; the peril was sudden and couldn’t have been predicted or prevented. A home insurance policy covers this type of damage.
Common perils covered by insurance
In a named perils policy, 16 listed perils are covered, including storms, fire, sudden and accidental water damage, theft, falling objects and vandalism. In an open perils policy, all of the same perils are covered, but anything else that is not listed as specifically excluded is also covered.
The full list of the 16 named perils is:
- Windstorm or hail
- Fire or lightning
- Aircraft
- Riot or civil commotion
- Explosions
- Vandalism
- Smoke
- Vehicle damage
- Theft
- Falling objects
- Freezing
- Weight of ice, snow or sleet
- Sudden or accidental tearing, cracking, burning, or bulging
- Accidental discharge of or overflow of water or steam
- Sudden and accidental damage due to short circuiting
- Volcanic eruption
Named perils vs. all perils home insurance
A named perils policy includes coverage for only certain perils, while an all-perils policy covers damage from all perils not actively excluded.
A standard HO-3 home insurance policy is an all-perils policy. Sometimes known as all-risk or open perils coverage, this type of insurance will cover loss or damage caused by any and all perils that are not explicitly excluded from your policy. This applies only to the structure of the home; personal property is covered on a named perils basis.
Some types of home insurance, however, are named-perils policies, even for the dwelling. Those include policies for older homes or dwelling policies for vacation homes or rental homes. Renters insurance is also named peril coverage. In some cases, you can add an endorsement to include all-perils coverage.
“Most of the time you can add an endorsement for open peril coverage, and then whatever is in the exclusions which is normally like normal wear and tear, intentionally causing loss [won’t be covered],” says Kristen Gryglik, an insurance agent with Comparion Insurance Agency in Boston. “There’s usually eight to 10 exclusions. It means that instead of only covering you for 16 things, we’ll cover you for anything and everything except for the exclusions.”
The main benefit of open perils coverage over named peril coverage is that most losses will be covered. To deny a claim, your insurance company will have to prove that, despite having all perils coverage, a loss isn’t covered.
What perils are not covered by home insurance?
The most common peril that isn’t covered by a home insurance policy is flooding. While flood insurance may be required by your mortgage company if you live in a high-risk area, it’s a separate policy.
Water damage to your home is a peril that is covered in some instances and not in others, and it’s important to know the difference, which is in the source of the water.
Water from a burst pipe or leaky water heater, or that comes into your house when a storm causes roof damage, is covered. Water damage from overland flooding is not covered.
This shows how the hazard that caused the peril can determine whether it’s covered. Insurance companies are careful to give the perils different names to clarify the difference between covered and excluded perils, but it can still be confusing.
Earthquakes, also called earth movement in an insurance policy, are also not covered, but earthquake coverage can be added by an endorsement or purchased as a separate policy. Other commonly excluded perils are:
- Government action
- Intentional loss
- Neglect
- Nuclear hazard
- Ordinance or law
- Power surges that originate off your property
- War
- Water and sewer backup
Some of these can be added by endorsement, while others are never covered. Read your homeowners insurance policy carefully so that you know which perils it covers.
Are perils the same as risks or hazards?
No. While perils and hazards are connected, they are not the same. Perils are the events that cause damage to your home. A hazard is a situation that increases the likelihood of a peril happening.
Think of it this way: If a wood stove is defective and starts a fire that burns down your living room, the fire is the peril because it did the damage, and the wood stove is the hazard because it caused the peril to occur.
A risk, on the other hand, is the chance or probability of a loss. For example, a risk is a home that is located at a long distance from the nearest fire station. That means the house is at greater risk of fire damage, because the fire department will take longer to arrive and put the fire out.
In our example above, if the home with the wood stove is located in a remote area, it has a higher risk of fire, the wood stove is a hazard that increases the risk of fire, and when a fire happens, it’s a peril.
FAQ: Perils and home insurance
Why does home insurance exclude some perils?
Insurance companies usually exclude specific perils because the risk is too great and the cost of claims is too expensive. Flood is an example; insurance companies removed flood coverage from standard home insurance policies because it costs too much to pay the claims compared to what the insurer can charge in premiums.
What's the difference between flood damage and water damage?
The difference between flood damage, which is not covered by home insurance, and the water damage that is covered by home insurance is the source of the water. Flood water comes from an overland source outside the home, such as a river overflowing its banks or a storm surge. Water damage, as defined by a home insurance policy, comes from a sudden, accidental source, such as a burst pipe or a storm that breaks a window and allows rainwater to enter the home.
Can I get all perils coverage for my personal property?
Yes. Many insurance companies offer all-perils coverage as an endorsement on an HO-3 policy. Alternatively, you can purchase an HO-5 home insurance policy that automatically includes all-perils coverage.
 Helpful home insurance tools and calculators