

- What is an underwater mortgage?
- Is there insurance for underwater mortgages?
- What causes a home to be underwater?
- What happens if your house is worth less than your mortgage?
- Does being underwater on your mortgage affect home insurance?
- What states have the most seriously underwater homes?
- How to avoid an underwater mortgage
- FAQ: Underwater mortgages
What is an underwater mortgage?
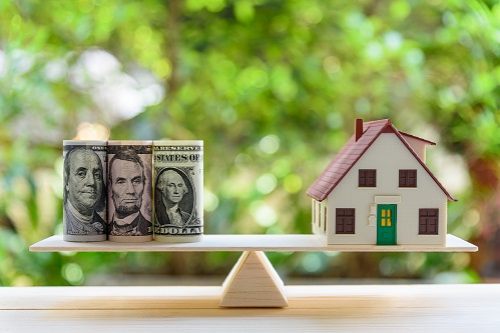
An underwater mortgage occurs when your outstanding mortgage balance exceeds your home's current market value.
For example, if your home's current market value is $280,000, but you owe $300,000 on the mortgage, your home is underwater or upside-down. You owe $20,000 more to your mortgage lender than your home would sell for. Putting that into even greater perspective, if you sold that home, you’d pay 100% of the sale proceeds on your mortgage loan, and then you’d still owe an additional $20,000 out-of-pocket.
You may also hear this situation referred to as negative equity. If you have equity in your home, that means the home is worth more in the current market than you owe on your mortgage. This is a great thing! But when you have negative equity, it means quite the opposite. It means you are underwater and that is not a good thing.
Is there insurance for underwater mortgages?
Homeowners insurance does not protect you against negative equity. It covers eligible losses to your home and belongings, subject to the policy's terms and limits, rather than the difference between your mortgage balance and your home's market value.
Some financial companies have offered underwater mortgage insurance in the past, but the product is very rare today. If you can find it, you need to purchase it before your home is underwater.
What causes a home to be underwater?
A home becomes underwater when its market value falls below the outstanding balance of the mortgage loan. Several factors contribute to that situation, including declining property values, a small down payment, and borrowing against home equity.
A housing market bubble burst
As a recent example, a housing bubble that peaked in the mid-2000s caused a dramatic increase in housing values and prices. When that bubble burst beginning around 2006–2007, many homeowners were left underwater on their mortgages, contributing to the 2008 housing crisis.'
Low down-payment loans
A standard conventional mortgage requires a down payment of 20%. A lower down payment, while available with some loans, increases the risk of being upside down on the mortgage if the house loses value.
Excessive refinancing or borrowing against the home
Borrowing against the home's equity reduces the amount of equity available and, therefore, increases the risk of becoming underwater if there are shifts in the housing market that cause a decline in values.
Missed payments
Missing your mortgage payments can cause interest to compound and accumulate, which increases what you owe. Missing mortgage payments also results in no reduction in your principal balance. The combination of no principal reduction and accrued interest charges can result in your loan amount growing instead of declining and can ultimately cause an upside-down mortgage.
Location
The location of your home can either increase or decrease your risk of an upside-down or underwater mortgage. This is usually the result of the local economy or a decline in neighborhoods that drives down property values.
According to John Romito, founder and real estate agent of Heart & Home Real Estate, "it can be difficult to even realize that a property has reached underwater status without having it appraised, but indications that problems are developing include falling property values among other homes in the area, and falling behind on payments. Falling behind can be particularly dangerous since falling too far behind on monthly payments can lead to the property being seized by the bank."
What happens if your house is worth less than your mortgage?
An underwater mortgage does not automatically require you to sell your home or pay the difference. Your next steps depend on your ability to afford the payments, your plans for the property, and your lender's requirements.
- Do nothing. If you're able to keep making the mortgage payments and have no plans to move, you can likely just wait it out. The market is likely to recover eventually.
- Refinance. It's difficult but not impossible to refinance an underwater mortgage. Talk to a mortgage expert about your options.
- Short-sell. A short sale is when you work with your lender to sell the house for an amount that it is willing to accept to clear the loan, even if it's less than you owe. It's important to know that a short sale will hurt your credit and may make it hard to get another mortgage for a few years.
- Work to build equity. To close the gap between what your house is worth and what you owe, consider making extra mortgage payments whenever possible and completing home improvements that will increase the value of the home.
Does being underwater on your mortgage affect home insurance?
No. Being underwater does not change your homeowners insurance eligibility or the replacement cost of your house. Homeowners insurance is based on the cost to repair or rebuild the home after a covered loss, not simply its market value or outstanding mortgage balance.
Homeowners insurance covers the house for its replacement cost, which is the amount required to rebuild it today. This amount may be higher or lower than the market value of the home, and higher or lower than the loan amount as well.
Even if the value of the home fluctuates, the amount needed to rebuild it isn't affected.
People ask
Should I reduce homeowners insurance coverage if I'm upside-down on my mortgage?
No. You need to insure your home for its replacement cost. However, you can shop around for a cheaper policy and put the extra money towards your mortgage.
What states have the most seriously underwater homes?
ATTOM's second-quarter 2026 report shows that the share of seriously underwater mortgaged homes varies significantly by state. Minnesota had the highest reported share at 12.1%, followed by Louisiana at 10.3% and Iowa at 7.8%. Nationally, 3.2% of mortgaged residential properties were seriously underwater.
| Rank | State | Q2 2026 % Seriously Underwater | Prior Quarter (Q1 2026) | Year Ago (Q2 2025) |
| 1 | Louisiana | 10.3% | 11.8% | 11.9% |
| 2 | Iowa | 7.8% | 6.0% | 5.9% |
| 3 | Mississippi | 6.4% | 8.0% | 6.5% |
| 4 | Arkansas | 6.0% | 6.4% | 5.6% |
| 5 | South Dakota | 5.7% | 3.0% | 3.1% |
| 6 | Kentucky | 5.7% | 8.5% | 7.0% |
| 7 | Nebraska | 4.8% | 4.3% | 3.8% |
| 8 | Oklahoma | 4.7% | 6.6% | 5.6% |
| 9 | Missouri | 4.5% | 4.9% | 4.3% |
| 10 | Alabama | 4.4% | 3.7% | 3.2% |
| 11 | Ohio | 4.4% | 4.3% | 3.8% |
| 12 | Illinois | 4.4% | 4.9% | 4.2% |
| 13 | Wisconsin | 4.2% | 3.5% | 3.3% |
| 14 | Kansas | 4.1% | 5.0% | 4.4% |
| 15 | West Virginia | 4.1% | 4.5% | 4.3% |
| 16 | Michigan | 4.0% | 3.1% | 2.5% |
| 17 | North Dakota | 4.0% | 4.3% | 5.0% |
| 18 | Pennsylvania | 3.6% | 4.3% | 3.7% |
| 19 | Indiana | 3.5% | 3.7% | 3.1% |
| 20 | Maryland | 3.5% | 3.8% | 2.6% |
| 21 | Tennessee | 3.3% | 3.7% | 3.0% |
| 22 | Georgia | 3.2% | 3.5% | 3.2% |
| 23 | Idaho | 3.2% | 2.8% | 2.4% |
| 24 | North Carolina | 3.1% | 3.1% | 2.5% |
| 25 | Maine | 3.1% | 2.5% | 2.1% |
| 26 | Virginia | 2.9% | 2.4% | 2.0% |
| 27 | South Carolina | 2.9% | 3.6% | 3.2% |
| 28 | New Mexico | 2.7% | 3.3% | 2.7% |
| 29 | Alaska | 2.6% | 2.2% | 2.0% |
| 30 | Delaware | 2.6% | 2.8% | 2.3% |
| 31 | Washington | 2.5% | 2.1% | 1.7% |
| 32 | Colorado | 2.5% | 2.8% | 2.3% |
| 33 | Utah | 2.4% | 2.6% | 2.4% |
| 34 | Wyoming | 2.4% | 2.4% | 2.6% |
| 35 | California | 2.3% | 1.7% | 1.4% |
| 36 | Texas | 2.1% | 2.6% | 2.3% |
| 37 | Florida | 2.1% | 2.4% | 1.8% |
| 38 | Arizona | 2.0% | 2.2% | 2.0% |
| 39 | Hawaii | 1.9% | 1.8% | 1.3% |
| 40 | Oregon | 1.9% | 2.2% | 1.8% |
| 41 | Montana | 1.9% | 1.9% | 2.0% |
| 42 | Nevada | 1.6% | 2.1% | 1.7% |
| 43 | New Jersey | 1.6% | 1.8% | 1.7% |
| 44 | New York | 1.5% | 1.9% | 2.0% |
| 45 | New Hampshire | 1.3% | 1.3% | 1.1% |
| 46 | Massachusetts | 1.3% | 1.5% | 1.1% |
| 47 | Rhode Island | 1.1% | 1.2% | 0.9% |
| 48 | Vermont | 0.9% | 0.7% | 0.7% |
How to avoid an underwater mortgage
You cannot control the housing market, but you can reduce your risk of negative equity by borrowing carefully and monitoring your loan balance
There are some things you can do, including:
- Put the biggest down payment you can on your home when you buy it
- Make bigger mortgage payments than necessary if you can, and make extra payments whenever possible
- Work to improve your home's value by keeping up on maintenance and completing upgrades
- Don't take out second mortgages or home equity loans
- Carefully review property value trends in the areas you are considering before you buy
Sources:
ATTOM. "Percent of properties seriously underwater by state 2026." Accessed October 2026.
FAQ: Underwater mortgages
What insurance should I keep if I’m going through foreclosure?
Keep your homeowners insurance active while you own the home and remain responsible for it, subject to your policy terms and lender requirements. A lapse in coverage might violate your mortgage agreement and lead the lender to purchase force-placed insurance, which often costs more and provides less protection than a standard homeowners policy.
Will my homeowners insurance cover me if I owe more than my home is worth?
No. Your homeowners insurance will cover the replacement cost of your home, which is not related to your mortgage balance. In a total loss, the insurance policy will pay out the dwelling coverage amount listed on the policy, not your loan balance. Remember that even if you lose the home, you still own the land, which has value as well.
 Helpful home insurance tools and calculators
In case you missed it
Stay updated with our latest insurance insights and guides
 October 1, 2026
Historic home insurance differs from standard home coverage because older homes often...
Read article September 29, 2026Landlord insurance covers rental properties, while homeowners insurance covers owner-occupied homes.
Read article September 25, 2026Vacant home insurance protects a property that is empty for an extended...
Read article