Gap insurance vs. loan or lease payoff
Gap insurance and loan/lease payoff coverage both help when you owe more on your car than it is worth after a total loss or theft. The main difference is how much they will pay. Gap insurance usually pays the full remaining shortfall. Loan/lease payoff coverage usually has a limit and may only pay a set percentage of the car’s value.
According to Progressive, lease/loan insurance often pays about 25% of the vehicle's actual cash valueActual Cash Value (ACV) is the current market value of your car, considering depreciation. It's the amount your insurance will pay if your car is totaled or stolen.. Depending upon where you are in your loan repayment process and how that compares to your vehicle's cash value, this may or may not be enough to cover your remaining loan or lease value in the event of a complete loss.
For example, if your car is worth $25,000 and your lease/loan coverage pays up to 25% of your vehicle's worth, the maximum payout in the event of a total loss would be $6,250. During the early part of your loan, this coverage amount may not provide complete protection.
Gap insurance vs. new car replacement
Gap insurance pays off what you still owe on your loan if your car is totaled, after the insurance settlement is paid. New car replacement insurance helps you get a new car instead of just the car’s depreciated value. Gap insurance covers the difference between your loan balance and the car's value. New car replacement gives you more money toward buying a similar new car. It does not always cover your entire remaining loan balance.
Collision and comprehensive insurance pay the car’s actual cash value if it is totaled, minus your deductibleThe deductible is the amount you pay out of pocket for a covered loss when you file a claim.. Actual cash value is the car’s pre-accident worth after depreciationDepreciation is the decrease in your car's value over time due to wear and tear, age and mileage. Depreciation is used to determine the actual cash value of a vehicle in the event of a total loss. (loss in value over time). This payment is often less than what you owe on your loan and also less than the cost of buying a new car.
New car replacement coverage is different. It covers the difference between the car's cash value and the cost of purchasing that exact car brand new. When you drive a new car off the lot, it officially becomes a "used" car and loses value immediately. If you total your new car on your way home from the dealership, the car's cash value would be less than the cost of replacing it. Replacement coverage would make up the difference, allowing you to buy another car exactly like the one you totaled.
However, this has nothing to do with your loan amount. If your loan balance exceeds the car's replacement value, you'll still have to pay your lender unless you have gap insurance. The illustration below shows what happens when you total your car with gap insurance.
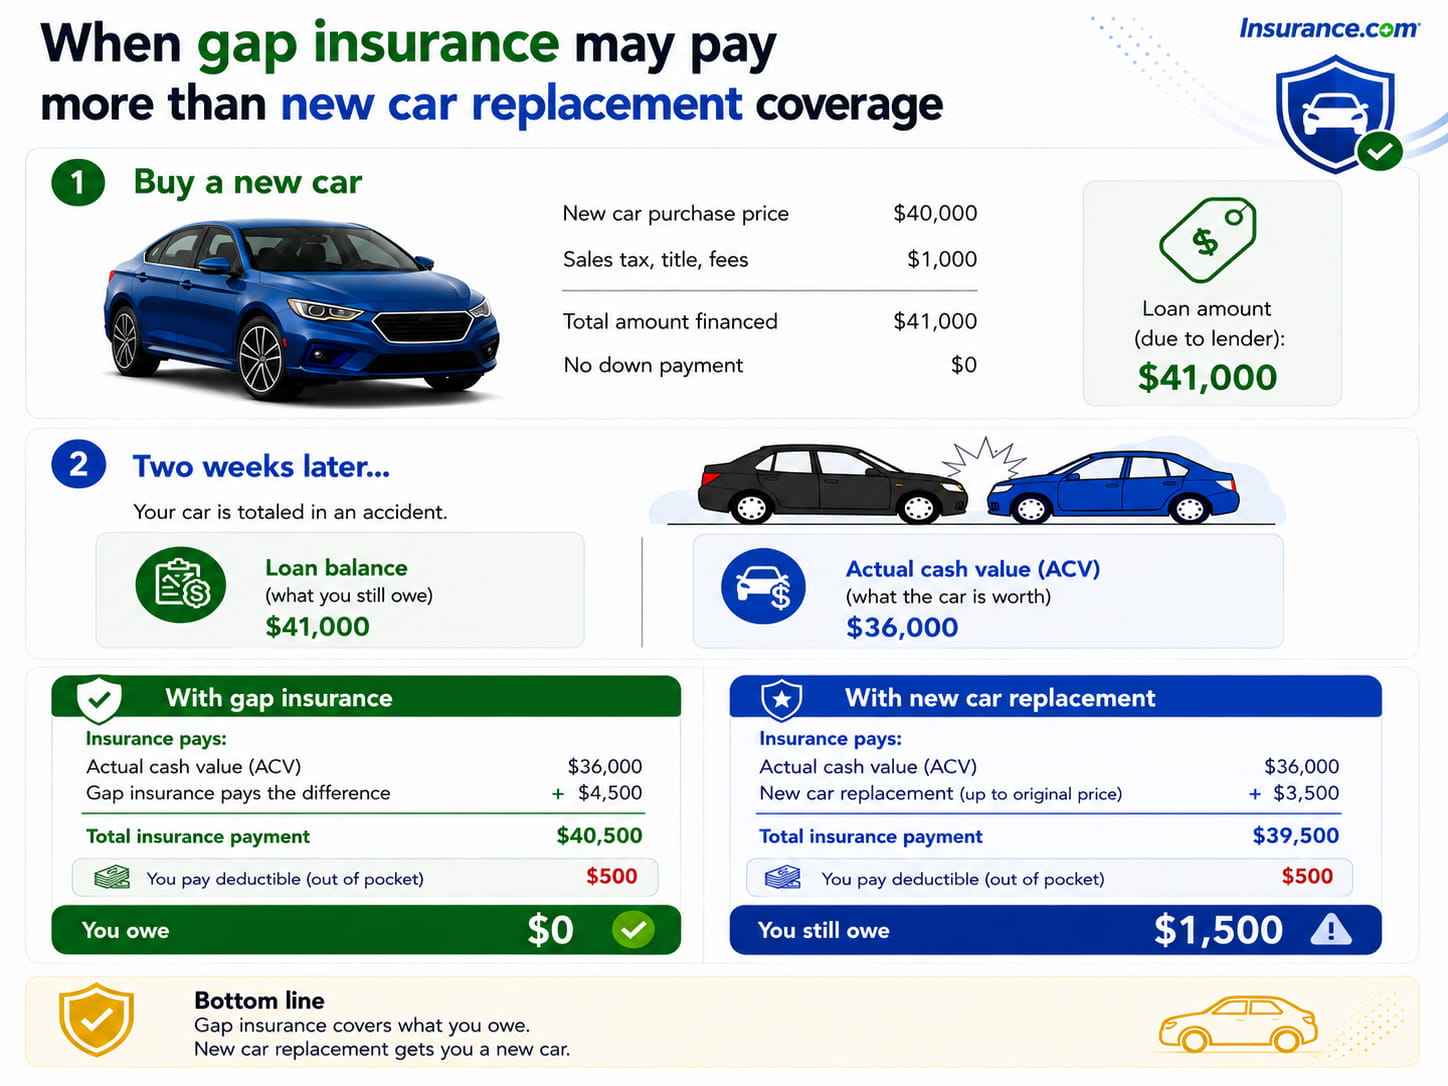
If the cost to replace your car is higher than your loan balance, it may be best to have new car replacement coverage. The illustration below differs from the one above in that the replacement costThe cost of replacing or repairing lost or damaged property with like kind and quality at today’s price without depreciation. is higher than the loan balance.
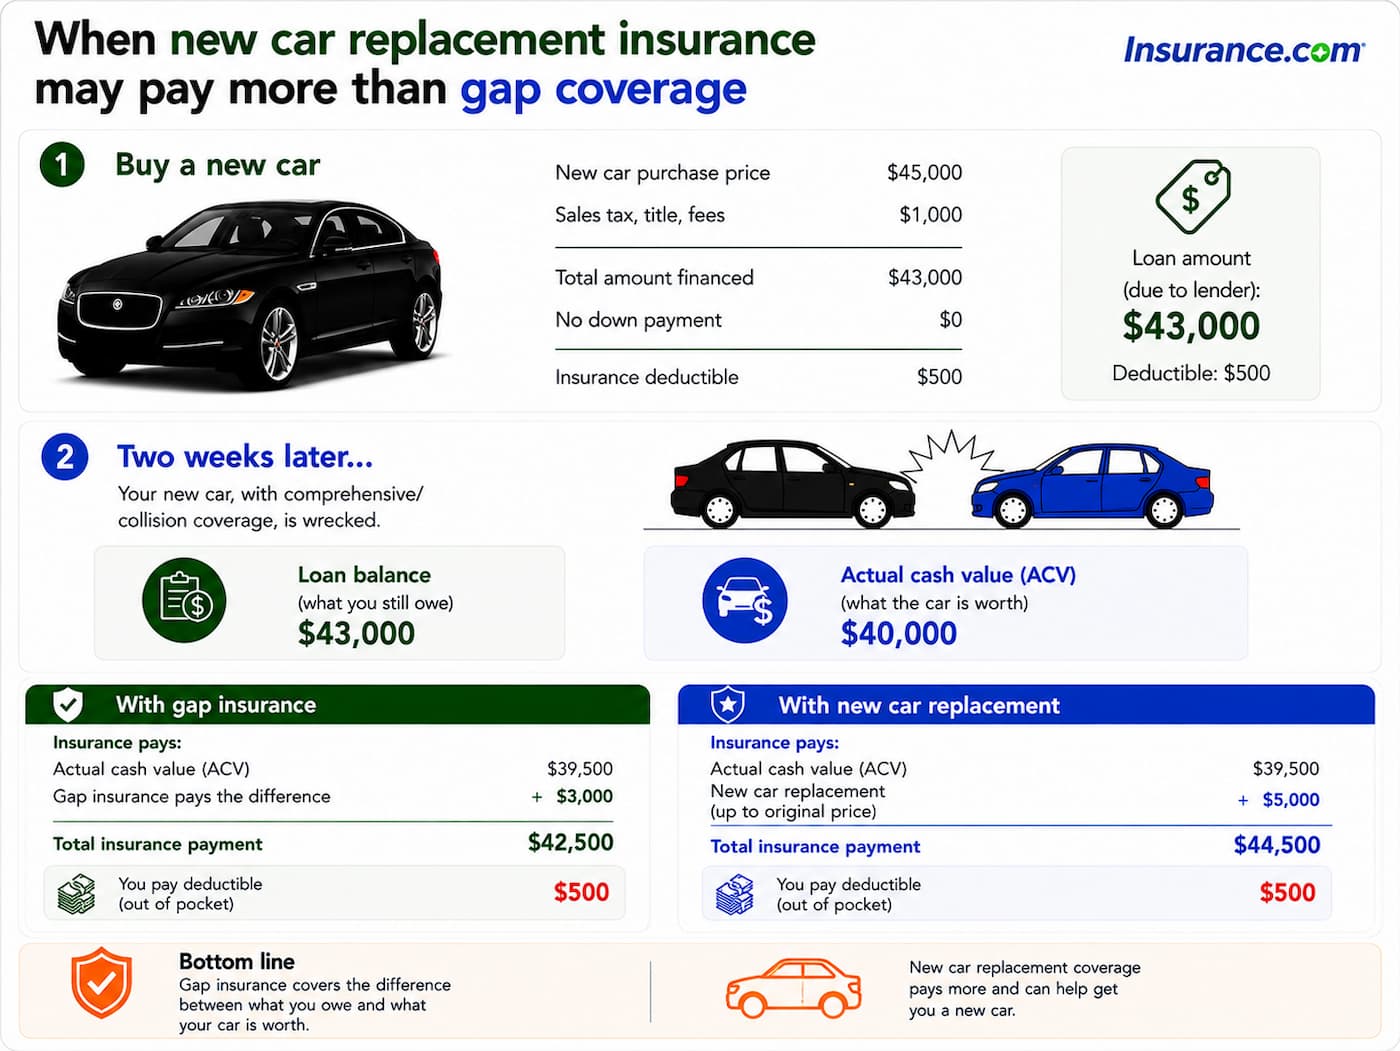
The comparison between gap and new car replacement depends on the loan balance and the car's depreciation rate. If your loan amount exceeds the car's purchase price, gap insurance should pay more. If the loan is less than the car's replacement price, new car replacement may pay more.
Which coverage should you choose?
If you are concerned about paying off your loan after a total loss, choose gap insurance or loan/lease protection, and if you’re more concerned about replacing your car with a new one, choose new car replacement. If you’re worried about both sides of the issue, you can buy a combination of coverage: gap insurance or loan/lease coverage and a new car replacement endorsement on your car insurance policy.
Consider gap insurance when:
- You owe much more than the car is worth.
- You made a small down payment.
- You financed the vehicle for a long term.
- You included previous loan debt in the new loan.
Consider loan/lease payoff coverage when:
- Your insurer does not offer full gap coverage.
- Your negative equity falls below the policy’s payout limit.
- You want to add the coverage to your existing auto policy.
Consider new car replacement coverage when:
- You own an eligible new vehicle.
- You want another new car after a total loss.
- You don’t want to cover the difference between actual cash value and replacement cost.
- Your remaining loan does not greatly exceed the replacement value.
If you are concerned about both paying off a loan or lease and being able to buy a new car, buy a combination of coverage. Choose either gap insurance or loan/lease payoff in addition to a new car replacement endorsement, if it’s available from your carrier.
FAQ: Gap insurance vs. loan/lease coverage vs. new car replacement insurance
Is loan/lease payoff coverage the same as gap insurance?
No. Both cover an eligible loan or lease shortfall after a total loss, but loan/lease payoff coverage often has a lower payout cap. Progressive, for example, limits payment to 25% of the car’s value, subject to state rules. Gap contracts also contain limits and exclusions, so compare the actual terms.
Does new car replacement insurance pay off your loan?
No. New car replacement coverage bases the claim payment on the cost of another new equivalent vehicle instead of the totaled car’s depreciated value. The lender receives the full settlement amount as payment, but you remain responsible for any loan balance that exceeds the covered replacement amount.
Do you need gap insurance if you have new car replacement coverage?
Yes, you may still need gap insurance if the remaining loan balance exceeds the new-car replacement settlement. New car replacement raises the vehicle payout but does not guarantee the full loan balance will be paid. Compare your current payoff amount with the policy’s replacement-value calculation before deciding.
 Helpful auto insurance tools and calculators